IUL for retirement income, explained in plain English.
You have probably seen “IUL” online, and everyone seems to say something different. IUL is the tool I use to explain retirement income from policy loans. Policy loans are generally not taxed as income under current tax law, which is why many people use them for retirement income instead of withdrawing taxable money. Loans accrue interest and reduce the death benefit if unpaid, a lapse or MEC status can make them taxable, and a CPA should confirm. Let me walk you through how it really works, what it costs, and who it fits. I will also tell you who it does not fit.
See if this is a fitIn one minute
- It is permanent life insurance with a cash value part
- Interest is credited based on an index, with a cap, and you are not in the market
- Policy loans are generally not taxed as income under current tax law, but loans accrue interest and a lapse can make them taxable
- Costs, limits, and risks are real, and we cover them
- Coverage is subject to underwriting and approval
Free. About 30 minutes. Virtual or by phone. No pressure, no obligation.
IUL is explained in confusing ways.
Some people say an IUL is a magic money machine. Others say it is a scam. Both are loud, and neither helps you decide.
You are trying to do right by your family. You deserve a clear, calm explanation with the good and the bad in the same place.
Pay in. Pay costs. Earn interest.
You pay premiums
You pay into a permanent life insurance policy. You choose how much to fund, within limits set by the policy and the tax code.
Costs come out
Each month the policy takes out the cost of the insurance and other fees. What is left goes into the cash value.
Interest is credited
Once a year or so, the policy credits interest to your cash value. The amount depends on how an index did, within the limits below.
Under Section 7702 of the tax code, which defines life insurance for tax purposes, a policy has to keep a mix of death benefit and cash value to qualify as life insurance. That is why there are limits on how much you can fund, and putting in too much too fast can make a policy a modified endowment contract (MEC), which changes how loans are taxed.
Borrow against the policy instead of withdrawing taxable money.
Build for years
You fund the policy over many years, so the cash value has time to build. Interest is credited based on an index, with a cap.
Borrow in retirement
Instead of withdrawing taxable money, you may take policy loans against the cash value. Policy loans are generally not taxed as income under current tax law, which is why many people use them for retirement income instead of withdrawing taxable money. That depends on the policy being properly structured and maintained.
Manage it every year
Loans accrue interest, and unpaid loans reduce the death benefit. A policy that is not managed can lapse, and a lapse or MEC status can make loans taxable. We review it with you each year.
Nothing here is a promise of income. How much you could borrow depends on how much cash value the policy builds, which is not guaranteed. Tax rules can change, and a lapse or MEC status can make loans taxable, with a tax bill on a lapse with loans outstanding. Please review it with a CPA before you fund a policy or take a loan. Not right for everyone.
Already have retirement savings and worry about a market drop? That is a different question, and a different tool. See Retirement Protection, which is about protecting savings you have already built.
Three words, in plain English.
Floor
The lowest interest rate the policy can credit for the period. Many policies use a 0% floor. That means a down year in the index does not take interest away. The monthly costs still come out, so cash value can still go down.
Cap
The most interest the policy can credit for the period. If the cap is 10% and the index rose 14%, you would be credited 10%. The upside is capped, and the cap can change.
Participation rate
The share of the index gain the policy counts. If the rate is 80% and the index rose 10%, the policy would count 8%, and then the cap still applies.
These numbers are examples only. Real caps and rates differ by policy and can change over time. Credited interest is not guaranteed. And you are not buying stocks. The index is only used to measure how much interest to credit.
Every policy has costs. Know them up front.
Cost of insurance
The charge for the death benefit. It generally goes up as you get older.
Policy fees
Administrative charges and charges for any added features (called riders).
Early-year charges
Many policies charge you if you cancel in the early years, so cash value can be low at first.
Loan interest
If you borrow from the policy, interest is charged on the loan. Unpaid loans, interest, and withdrawals reduce cash value and death benefit.
The risks, in short.
- Credited interest is not guaranteed, the upside is capped, and it can be lower than the illustration shows. Retirement income from loans is not guaranteed either.
- It takes years for cash value to build. Early on, you may have little you can reach.
- Loans accrue interest and can reduce the death benefit. If you under-fund the policy or borrow too much, it can lapse. A lapse can lead to taxes and the loss of coverage.
- Tax treatment depends on current tax law and your situation, and it can change. A CPA should review it before you buy.
- It is not right for everyone.
- It is not a quick fix, and it is not a direct investment in the market.
- You must qualify. Coverage is subject to underwriting and approval.
Honest about fit.
This may be a good fit if you:
- Already have your mortgage and basic protection handled
- Have steady cash flow and an emergency fund
- Can fund a policy for many years without strain
- Want protection for your family and a place to build cash value that you may later borrow against for retirement income
- Understand that results are not promised
This is probably not for you if you:
- May need this money in the next few years
- Cannot fund it steadily for years
- Have no emergency fund yet
- Want guaranteed investment returns
- Mainly want to protect retirement savings you already have from market loss (see Retirement Protection)
- Want only the lowest-cost term coverage
- Expect fast results
Design depends on your goal.
Built for debt
Debt Free Life uses a different structure: a high cash value whole life policy with guarantees written in the contract. See Debt Free Life.
Built for college
A cash value life insurance policy designed for a long runway, so cash value may be there when tuition comes due. See College Funding.
Built for retirement income
This is where IUL fits best. Designed so that policy loans can be used for income later. They are generally not taxed as income under current tax law, but a lapse or MEC status can change that. A CPA should review it.
Built for legacy
Designed with more weight on the death benefit, often with an attorney and a CPA. See Build It Right.
Ask how any policy is designed and how your agent is paid. Two policies with the same death benefit can have very different cash value depending on design (more cash-value-focused vs more death-benefit-focused).
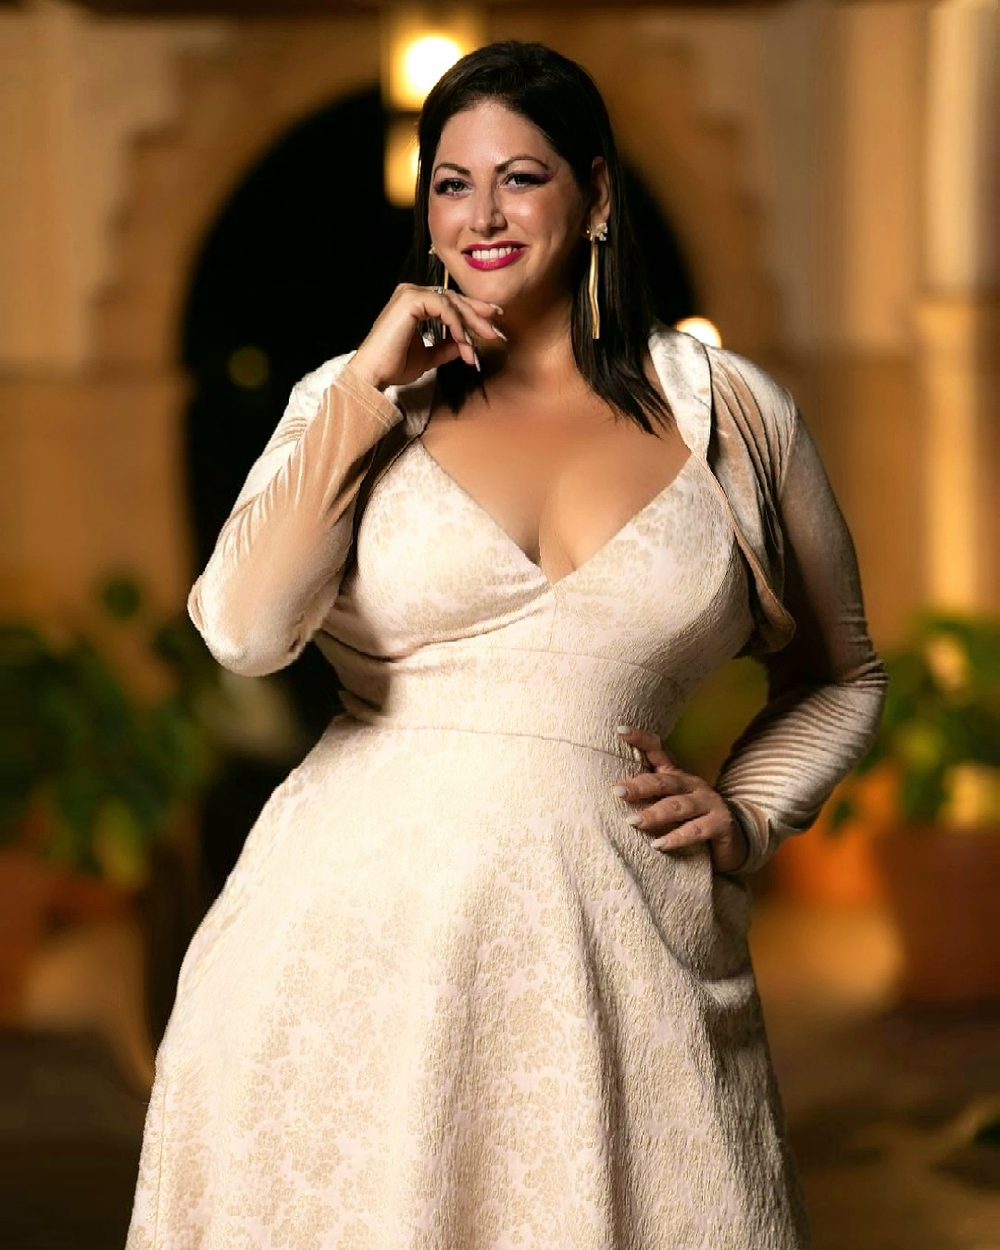
I explain it the way I wish someone had explained it to me.
Barbara Sarti
Florida licensed life insurance agent
Founder, Crowned Empire
License W788222 · NPN 200990589
A high cash value policy is the reason I became an agent. I saw how it can change the way a family handles debt, retirement income, and the future. I also saw how confusing it is when nobody explains the costs.
My job is to show you real numbers and the trade-offs, in everyday words. If a policy is not right for you, I will say so.
Three simple steps.
Book a free call
Pick a time that works for you. It is a calm, 30-minute talk about your goals and your family.
See how it would be built
I show you how a policy could be designed for your goal, with the costs and the risks in plain view.
Decide what fits
You choose what, if anything, makes sense. No pressure and no obligation.
4 quick questions.
You do not have to guess. Answer four quick questions and you will see whether a call makes sense now, or what a good first step looks like.
Your answers stay on this page.
Cash value policies generally work best when you can fund them consistently for years. If you’re earlier in the journey, I’ll point you to the right first step.
A policy you do not understand is a risk.
If you wait and guess
- You buy something built for the wrong goal
- You find out about the costs years later
- The policy lapses because it was never funded well
If you plan with open eyes
- You know how it is built and how your agent is paid
- You know the costs, the limits, and the risks
- You choose a design that matches your goal
What to know before you decide
Cash value policies are long-term. Building cash value usually takes years, and policies have costs and fees. Credited interest and illustrated values are not guaranteed, and the upside is capped. Policy loans accrue interest, and loans and withdrawals reduce the cash value and the death benefit. A policy can lapse if it is not funded properly or loans grow too large, which can have tax consequences. An IUL is not a direct investment in the market and is not right for everyone. Any tax advantage depends on current tax law and your situation, and it is not guaranteed, so please speak with a CPA or tax professional. Crowned Empire shares education only and does not give legal or tax advice. Coverage is subject to underwriting and approval. If your mortgage and basic protection are not handled yet, start there first.
Good to know.
Can IUL be used for retirement income?
Some people use it that way. Policy loans are generally not taxed as income under current tax law, which is why many people use them for retirement income instead of withdrawing taxable money. But loans accrue interest and reduce the death benefit if unpaid, the policy can lapse if it is not managed, a lapse or MEC status can make loans taxable, the upside is capped and not guaranteed, and tax rules can change. Please review it with a CPA.
How is IUL different from Retirement Protection?
IUL is life insurance with a cash value part, and it is about building cash value and retirement income from policy loans over many years. Retirement Protection is a separate option: a principal-protected annuity contract, offered through The Dafoe Agency, for savings you have already built. The costs, risks, and rules are different.
Is an IUL the stock market?
No. The policy does not buy stocks. An index is only used to work out how much interest to credit, within the floor, cap, and participation limits.
Can I lose money in an IUL?
The credited interest has a floor, so a down year in the index does not by itself lower your interest below that floor. But you can still end up with less than you paid in, especially in the early years, because of costs, or if you cancel early or the policy lapses.
How is an IUL different from term insurance?
Term covers you for a set number of years and has no cash value. An IUL is permanent insurance with a cash value part, and it costs more. Term is often the right answer, and I will tell you if it is.
How long does it take to build cash value?
Usually years. The cost of insurance and early-year charges come out first, so cash value is often small at the start.
What happens if I stop paying?
The policy can lapse if there is not enough cash value to cover the monthly costs. A lapse can mean losing coverage and, in some cases, owing taxes. Ask how the policy would hold up if you missed payments.
How do I compare two policies?
Ask how any policy is designed and how your agent is paid. Two policies with the same death benefit can have very different cash value depending on design (more cash-value-focused vs more death-benefit-focused).
Is the call free?
Yes. It is free, about 30 minutes, with no obligation.
IUL Basics: 7 Questions to Ask Before You Buy
A short, plain-English checklist of the questions to ask any agent before you buy an IUL, including for retirement income.
We never sell your information. See our Privacy Policy.
Get a clear answer on IUL.
Free, about 30 minutes, virtual or by phone. No pressure, no obligation.
See if this is a fit