Is the money you’ve already built protected?
You spent years building your 401(k), your IRA, and your investments. As retirement gets closer, it is fair to ask what would happen to that money if the market dropped. I’m Barbara Sarti. I will walk you through your options in plain words, with a licensed professional from The Dafoe Agency.
Free. About 30 minutes. Online by Google Meet. No pressure, no obligation.
In one minute
- It is a contract with an insurance company
- The type we cover protects your principal from market loss, subject to the contract terms and the insurer’s claims-paying ability
- It may earn interest linked to an index, but the upside is limited and not guaranteed
- It has trade-offs, like surrender charges and limited access to your money
- It is not right for everyone
Free. About 30 minutes. Online. No pressure, no obligation. Prefer to read first? Get the free guide.
Have you ever asked yourself…
Did your retirement account drop the last time the market did?
Many people watched a balance fall and felt it. Noticing that is not a mistake. It just tells you the question is worth asking.
If the market fell 20% next year, how long could you wait to get it back?
The answer depends on time. Someone 25 years from retirement and someone 3 years away have very different answers.
How close are you to needing this money?
The closer the date, the less time there may be to recover from a big drop. Your timeline matters more than anyone’s opinion.
Who is responsible for protecting what you’ve already built?
Your plan provider holds the account. How much risk you carry is generally up to you, and most people have never been asked.
There are no wrong answers here. These are just the questions most people have never said out loud.
You did the hard part. Now comes the quiet part.
Saving for years took discipline. Investing in the market is how many people grow their savings, and nothing here says otherwise.
But as retirement gets closer, some people want to know whether part of what they’ve built could be shielded from a big drop. Others decide their current mix is right for them. Both are fine. This page helps you understand one option so you can decide for yourself.
This page is about protecting savings you have already built from market loss. If you want to build retirement income going forward from policy loans, that is a different tool: see IUL for retirement income.
Retirement protection, in plain words.
A contract with an insurance company
You put money into a contract and the insurance company agrees to certain terms in writing. This type is generally called a fixed indexed annuity. It is not a stock, a fund, or a bank account, and it is not FDIC insured.
Your principal is protected from market loss
Protected from market loss, subject to the contract terms and the insurer’s claims-paying ability. In the years the index goes down, there are no market losses on your principal, as long as the contract terms are met.
Interest is linked to an index
The contract may earn interest based on how a market index performs. Your money is not invested in the index itself. The upside is limited and not guaranteed, and in some years you may earn little or no interest.
The guarantees depend on the insurer
Any guarantee is backed by the insurance company’s claims-paying ability, not by the government. Ask about the company’s financial strength ratings and read the contract before you decide.
Three words, in plain English.
Cap
The most interest the contract can credit for the period. If the cap is 8% and the index rose 12%, you would be credited 8%.
Participation rate
The share of the index gain the contract counts. If the rate is 70% and the index rose 10%, the contract would count 7%, and the cap still applies.
Floor
The lowest interest that can be credited for the period. Many contracts use 0%, so a down year in the index does not reduce your principal through market loss.
These numbers are examples only. Real caps and rates differ by contract and insurer, and they can change over time. Interest is not guaranteed.
Three simple steps.
Get the free guide
A short 4-page guide with the questions to ask about your current accounts and about any principal-protected contract. Read it on your own time.
A short call with Barbara and Leroy
A free three-way Google Meet call, about 30 minutes. I open, Leroy Dafoe of The Dafoe Agency leads the conversation, and I listen in. Bring your questions.
You decide, no pressure
Take your time. Talk with your CPA or tax professional. Then choose what fits, or choose nothing at all.
4 quick questions.
You do not have to guess. Answer four quick questions and you will see whether a call makes sense now, or what a good first step looks like.
Your answers stay on this page.
Protecting retirement savings generally works best when there is a meaningful amount already set aside. If you’re earlier in the journey, I’ll point you to the right first step.
A conversation, not a sales pitch.
What we will not do
- Pressure you to decide on the call
- Tell you to move money out of your 401(k) or IRA
- Promise returns or hide the trade-offs
- Talk down the stock market or your current accounts
What we will do
- Ask about your timeline and your comfort with market swings
- Explain how principal-protected contracts work, with the limits in plain view
- Answer your questions honestly, including “this may not be for you”
- Point you to your CPA or tax professional for the tax questions
What to know before you decide.
- Surrender charges. If you take out more than the contract allows during the surrender period, you may pay a charge. Your access to your money may be limited for that period, which is set by the contract.
- Withdrawal limits. Most contracts allow a limited amount each year without a charge. Amounts above the limit may be charged.
- Taxes and penalties. Moving retirement money may lead to taxes and penalties, depending on how it is done and your situation. Please review it with a CPA or tax professional first.
- Limited upside. Caps and participation rates limit how much interest you can be credited, and interest is not guaranteed. In strong market years you may earn less than the market.
- Optional riders may carry fees. Extra features, such as income riders, often cost extra. Ask for every fee in writing.
- Depends on the insurer. Guarantees rely on the insurer’s claims-paying ability. Contracts are not FDIC insured.
- Not right for everyone. If you may need quick access to this money, it may not be a fit. Contracts differ, so read the terms and ask about the free-look period.
Retirement protection options are provided through The Dafoe Agency, licensed in Florida. Crowned Empire connects you with licensed professionals; Barbara Sarti, FL License W788222. Not legal, tax, or investment advice.
Honest about fit.
This may be worth a conversation if you:
- Are within a few years of retirement, or already retired
- Have a 401(k), IRA, or other investments you built over many years
- Would like to understand how part of that money could be shielded from big market drops
- Are comfortable giving up some upside for more certainty
- Have an emergency fund that is separate from this money
- Can leave the money alone through the surrender period
This is probably not for you if you:
- May need quick access to this money
- Want the full growth potential of the market
- Want a promise of high returns
- Have no emergency savings yet
- Are being rushed to decide
- Do not want a CPA or tax professional to look at it first
- Mainly want to build retirement income over time from policy loans (see IUL)
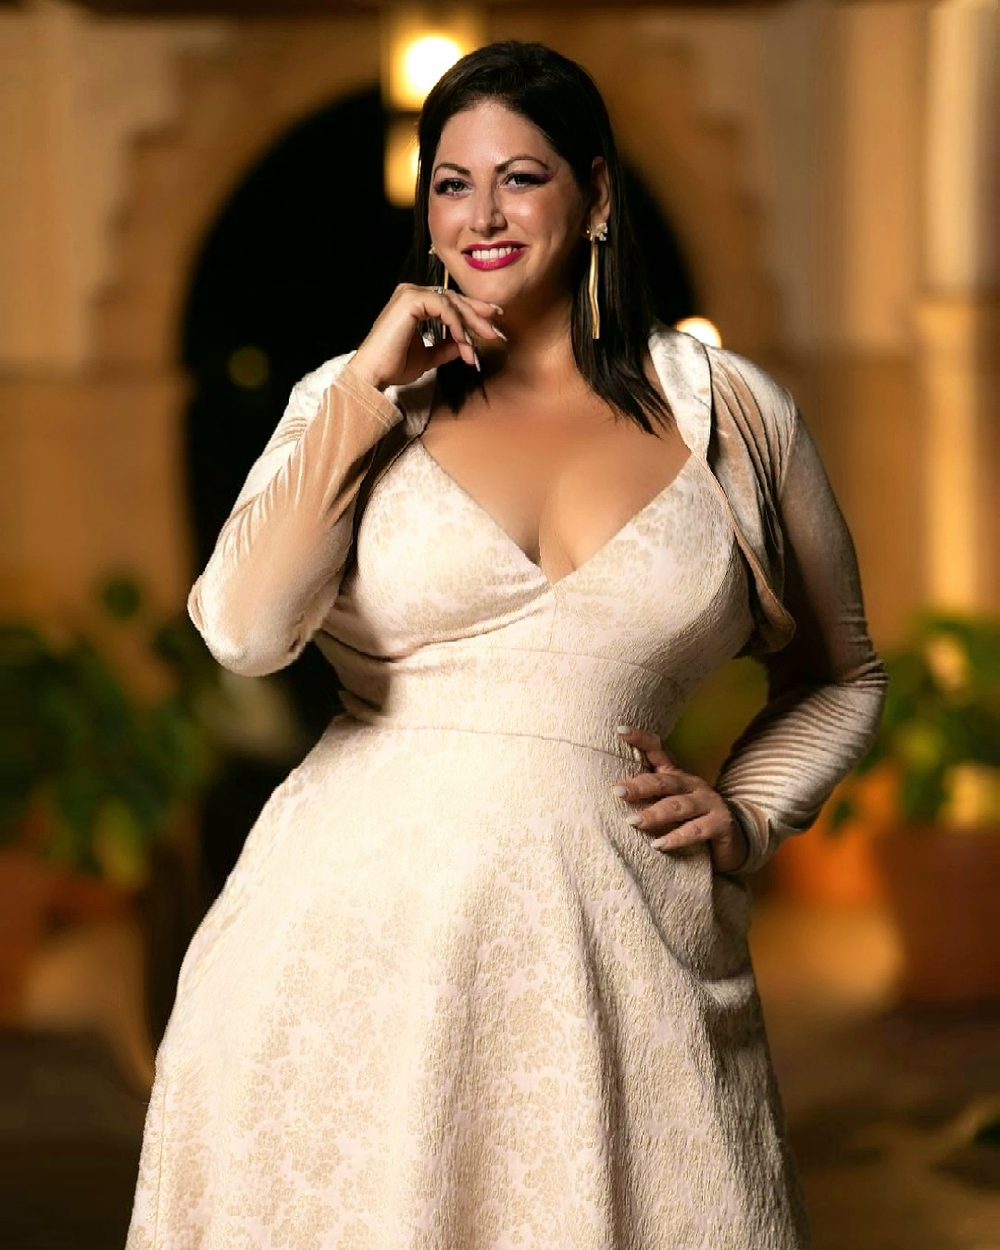
I would rather you ask good questions than make a quick decision.
Barbara Sarti
Florida licensed insurance agent
Founder, Crowned Empire
License W788222 · NPN 200990589
Many people I meet have spent decades building a 401(k), an IRA, or investments, and no one has ever sat down and asked how protected it is. My job is to explain things in everyday words and to tell you honestly when something is not a fit.
I am not the one who sells retirement protection contracts. Leroy Dafoe of The Dafoe Agency, licensed in Florida, does. On your call I open, Leroy leads, and I stay on to listen and make sure your questions get answered.
What people usually ask.
Is this the same as an IUL?
No. Retirement protection, as described here, is a principal-protected contract with an insurance company for savings you have already built. An IUL is life insurance with a cash value part, used to build cash value and retirement income from policy loans over many years. They are different products with different costs, risks, and rules, and you do not need one to consider the other.
Is this an annuity?
The type we talk about is generally called a fixed indexed annuity. It is a contract with an insurance company. I use the words “retirement protection” because that is what most people want to know about: how the money is protected, and what the trade-offs are.
Is my money in the stock market?
No. Your money is not invested in stocks or in the index. The index is only used to work out how much interest, if any, may be credited, within the contract’s limits.
Can I lose money?
Your principal is protected from market loss, subject to the contract terms and the insurer’s claims-paying ability. But you can end up with less in other ways: surrender charges if you take out more than the contract allows, fees for optional riders, and taxes or penalties. Ask about each one.
How much interest could I earn?
It depends on the contract. Interest is linked to an index and limited by caps or participation rates, which can change. It is not guaranteed, and in some years it may be little or nothing.
Do I have to move my 401(k) or IRA?
No. Nobody has to move anything, and I will never tell you to. The call is about understanding your options. If you ever consider moving retirement money, talk with your CPA or tax professional first, and ask what your current plan allows.
Who will be on the call?
Three of us: you, me, and Leroy Dafoe of The Dafoe Agency. I open the call, Leroy leads the conversation, and I listen. It is a free Google Meet call of about 30 minutes, and you can join from a phone, tablet, or computer.
Is this available outside Florida?
Right now we are set up to help people in Florida. If you live somewhere else, you are welcome to read the guide, but we may not be able to help with a call yet.
What if I decide it is not for me?
Then the call did its job. You will know more than you did before, and there is nothing you have to do next.
Is the call free?
Yes. It is free, about 30 minutes, with no obligation.
Questions to Ask Before You Move or Protect Retirement Savings
A free 4-page guide. It covers the questions to ask about your current accounts, five questions to ask any insurance professional about principal-protected contracts, what could go wrong, and the documents to gather. It does not tell you to move any money.
We never sell your information. See our Privacy Policy.
Ask the questions. Then decide.
Free, about 30 minutes, by Google Meet, with Leroy Dafoe of The Dafoe Agency and me. No pressure, no obligation.
See if this is a fitBack to home · Join the free Monday class
Not sure where to start? Book the free mortgage review
Retirement protection options are provided through The Dafoe Agency, licensed in Florida. Crowned Empire connects you with licensed professionals; Barbara Sarti, FL License W788222.